Rentvesting
Rentvesting is a real strategy. The guide tells you whether it’s yours.
More than half of first home buyers say they are considering it. The guide sets out what rentvesting actually is, the arithmetic that decides whether it works for a household like yours, and when it doesn’t.
What rentvesting is in plain English, and the trade offs
The gap between your rent and the repayments on that same home, and how to work out your own
Who it suits, and four signs it isn't you
70+
Years of property expertise
1954
Backed by Oliver Hume, est. 1954
290,000+
Australian buyers helped
4,800
Suburbs under research
The actual trade
Live here. Own there.
Most housing advice quietly assumes the home you live in and the property you own should be the same building. Rentvesting separates them.
Rentvesting, in plain English: renting the home you live in, while owning an investment property anywhere in Australia where the numbers stack up.
The key difference lies in intent. An owner-occupier purchase is often influenced by proximity to work, schools, amenities and social networks. A rentvesting purchase, by contrast, is usually assessed based on factors such as rental demand, infrastructure growth, supply constraints, and long-term market fundamentals. Shifting the focus to performance.
Many rentvestors focus on new property due to lower maintenance requirements, warranty protections and potential depreciation benefits, advantages established property can’t match.
The suitability of this strategy depends on income stability, risk tolerance, borrowing capacity and long-term objectives. We have no reason to push you toward one outcome over another, which is why we run the numbers against our 60 data point review process, across 4,800 suburbs.
WHAT IS INSIDE
Seven pages, 6 minutes to read
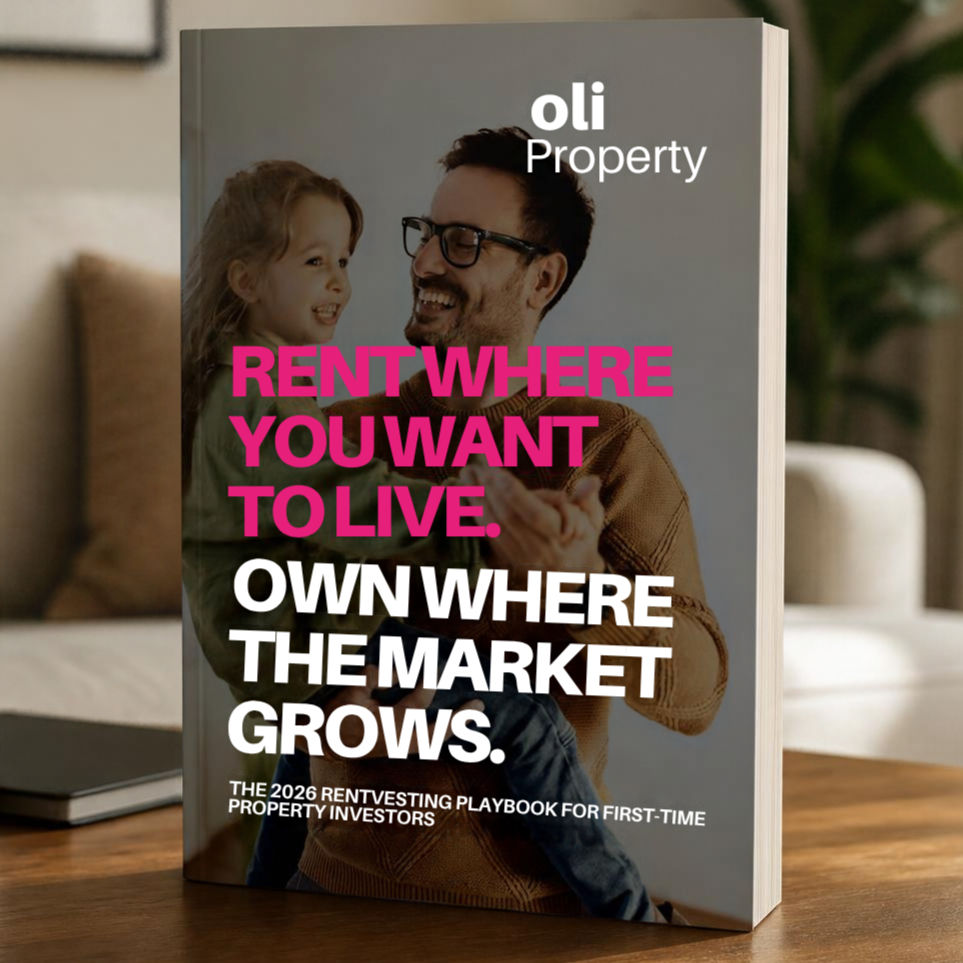
Rentvesting means renting the home that suits your life while owning an investment property anywhere in Australia where the numbers stack up. The 2026 Rentvesting Playbook from Oli Property walks through the strategy in plain English, backed by research across 4,800 suburbs. It opens with the definition, ends with your first step, and covers what decides the outcome in between:
What is rentvesting
The deposit treadmill and how leverage
Saving vs rentvesting: two paths compared
Key factors in investment property selection
Risks to understand
The Playbook at a glance
How do I start?
The numbers behind it
Three figures worth knowing before you read anything else
54%
of first home buyers say they are considering rentvesting. Westpac surveyed 2,000 Australians over December 2024 and January 2025. In New South Wales the figure was 61%
1.7%
of capital city house suburbs cost less to buy than to rent, on Domain research published in July 2025. That gap is the argument for rentvesting, and it is also the thing that can close
80%
at most, the share of your investment rent that most lenders count towards your borrowing capacity. Many shade it to 70%. Almost everyone budgets on all of it
Sources: Westpac media release, February 2025, sample of 2,000 Australians aged 18 and over. Domain Buy or Rent Report, July 2025. Lender shading policy varies between lenders and changes over time, so your broker is the one who can tell you where you actually sit. There's no guarantees that any of these conditions hold.
THE HONEST PART
It works for some households and not for others
Chapter eight is the one most people skip to, so here it is in short. The guide goes through each of these in full detail.
IT TENDS TO WORK WHEN
-
You rent somewhere you could not realistically afford to buy, and the gap between your rent and the repayments on that same home is wide
-
You are comfortable renting for at least the next five years, because entry and exit costs need time to be absorbed
-
Your income is taxed at a higher marginal rate, so the deductions do more work for you
-
You would rather own something that performs than own nothing while you keep saving for the suburb you want
IT TENDS NOT TO WORK WHEN
-
You need the security of a home nobody can ask you to leave. No spreadsheet prices that, and it is a reasonable thing to want
-
You are counting on a First Home Owner Grant or a stamp duty concession, because buying an investment first can affect eligibility and the rules differ in every state
-
You expect to buy where you live within two or three years, so the transaction costs land twice inside a short window
-
You could not cover the shortfall in a month where the property sits empty and the rent on your own home still has to be paid
This is general information about which strategies tend to suit which situations. It is not financial or tax advice, it is not a recommendation about any property, and your own position depends on your circumstances. Take independent advice before acting on any of it.
IF YOU ARE BUYING SOON
The 2026 rules land hardest on a first investment purchase
Chapter six covers this in full, and there is a separate guide if it is the only thing you came for.
Negative gearing, from 12 May 2026
Losses on established investment properties bought after Budget night can no longer offset your salary from 1 July 2027. New builds are unaffected. Anything held before that date is grandfathered.
Capital Gains Tax, from 1 July 2027
The 50% discount is replaced by an indexation system for established homes bought after that date. New builds keep the choice between the two methods.
Why Oli Property
Research you can check, on stock most buyers never see
Oli Property is part of Oliver Hume Property Group, which has been researching and selling Australian residential property since 1954 and has helped over 290,000 Australians buy. Our Chief Economist Matt Bell leads research across 4,800 suburbs, published quarterly and relied on by government and ASX 200 companies.
Every property is scored against more than 60 data points through our Investment Review Process before it goes to a client. Most do not pass. The ones that do are frequently available off market, before they reach realestate.com.au.
For a rentvestor that combination matters, because your whole case rests on the investment property outperforming the one you chose not to buy. There are no guarantees that it will. The least we can do is make sure the numbers were checked properly.
Run your rentvesting numbers with someone who has no stake in the answer
Thirty minutes with a Property Investment Specialist. Bring what you pay in rent, what you earn and what you have saved. You will get a straight read on whether rentvesting is doing more for you than buying where you live would.
30 minutes, by phone
No pressure, just understanding your situation.
With Cam or Adam
Property Investment Specialists
Bring three numbers